This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

Question: I don’t want to do any work to my home when I sell it, should I offer it “as-is”?

Answer: Selling a property “as-is” in Northern Virginia carries a practical purpose and a contractual definition that may differ and/or carry unintended consequences.

Implied Definition

When sellers market a property as-is, they’re usually implying that they do not want the hassle of making repairs; sometimes they also want to convey that they won’t negotiate credits for repairs either. That does not automatically mean the buyer cannot inspect the property. The parties might agree to a pre-offer inspection or an inspection contingency that allows the buyer to void the contract.

As-is doesn’t necessarily mean that a property has problems, but sellers should understand that most buyers assume an as-is property has issues and will approach it accordingly.

Technical/Contractual Definition

In Northern Virginia’s Contingencies/Clauses Addendum you’ll find a section for selling “as-is” with the following selectable options:

  • Seller will not clean or remove debris. The standard is for the property to be free of trash/debris and broom clean.

  • The seller is not responsible for addressing any wood destroying insect/termite issues. The standard agreement requires the seller to pay for any damage from wood destroying insects.

  • The seller is not required to fix any Homeowners/Condo Association violations related to the physical condition of the property.

  • The buyer assumes responsibility for compliance with applicable smoke-detector laws and regulations.

  • The seller is not responsible for compliance with notices of violation from local authorities.

Many properties are marketed as-is, but it’s less common for the as-is clause(s) in the contract to be used. Calling a property “as-is” in the marketing does not make it so, only the contract does that.

Understand Your Choice

I often talk to homeowners who ask to sell as-is because they don’t want to deal with buyer repair requests but their home is in good condition and they don’t mind negotiating for repair credits or addressing a big ticket issue. In cases like this, declaring a home as-is can discourage buyers unnecessarily or possibly net sellers less money. A better approach is to communicate those expectations up-front with a buyer without calling the home as-is.

For buyers who come across an as-is sale, it’s important to ask the right questions to find out what the seller’s true intentions are. For example, will they allow a pre-offer inspection or a void-only inspection after contract? Do they intend to address HOA/condo violations? Make sure that you are pricing and negotiating contract terms based on the seller’s intention, not based on your assumptions.

Who Uses As-Is?

As-is sales are common in estate sales (seller may have limited knowledge of the property) or properties marketed towards builders/investors (flips or tear-downs). There are plenty of other appropriate use cases for a true as-is sale, but those are the most common that I see.
(more…)


This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

Question: I’m reading a lot of negative news about the housing market. What’s the good news?

Answer: I’ve written quite a bit recently about the weaknesses in our local housing market (link, link, and link). Buyers have pulled back, homes are taking longer to sell, and sellers are adjusting their expectations. For those who need to sell now, these challenges are real and immediate.

We’ve become accustomed to treating rising prices, immediate sales, and bidding wars as evidence of a good housing market. But those conditions also make it difficult for new buyers to enter the market, existing homeowners to change homes, and for buyers to understand what they’re buying.

A market that gradually becomes more affordable and gives households more time to make major decisions is a healthier market.

A Healthy Market is an Affordable One

In my July Affordability article, I argued that sustainable affordability comes from a slow, long-term shift in which prices rise slower than income rather than from a sudden policy change. Sustainable affordability is a long way off in the DC area, but a modest price correction (which we’re currently experiencing in most sub-markets) followed by slower growth, can help ease us into a healthier housing market and should not necessarily be framed as a bad market or cause for alarm.

Mortgage rates, taxes, insurance, and maintenance costs also affect affordability, so slower price growth alone won’t solve the problem. A slowdown driven by job losses would undermine the income growth needed to make this work, so it needs to be supported by a healthy economy.

A Healthy Market Provides Buyers Reasonable Protection

For much of the past 7-10 years (in Arlington/DC Metro), buyers have been pressured to make decisions on whether to buy a home within hours or days and significantly reduce or completely remove basic protections (contingencies like inspection, financing, and appraisal) because of how much leverage sellers held in negotiations.

A healthy market gives buyers time to make better decisions and room to negotiate basic protections into contracts.

Earlier this month, I wrote about home inspection negotiations becoming more common. Understanding the condition of a home before committing to buy it should be an ordinary part of the process, but many buyers waived or flew through inspections, absorbing substantial risk in the process.

Your Next Home Matters, Too

Many sellers are also buyers, buyers of a more expensive home. So lower prices don’t mean a worse overall move.

Suppose your current home is worth $900,000 and the home you want costs $1.5M. If both decline 3%, you receive $27,000 less on the sale but pay $45,000 less on the purchase.

Of course, those two homes may perform differently, and giving up a low mortgage rate can overwhelm any absolute dollar savings. But the point is worth remembering that maximizing your sale price isn’t the only measure of a successful move.

(more…)


This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

Question: Can you highlight the key market trends you’re seeing in the housing market?

Answer: Today we’ll look at three charts that describe what I’m currently seeing in the DC Metro, Northern VA, and Arlington housing market.

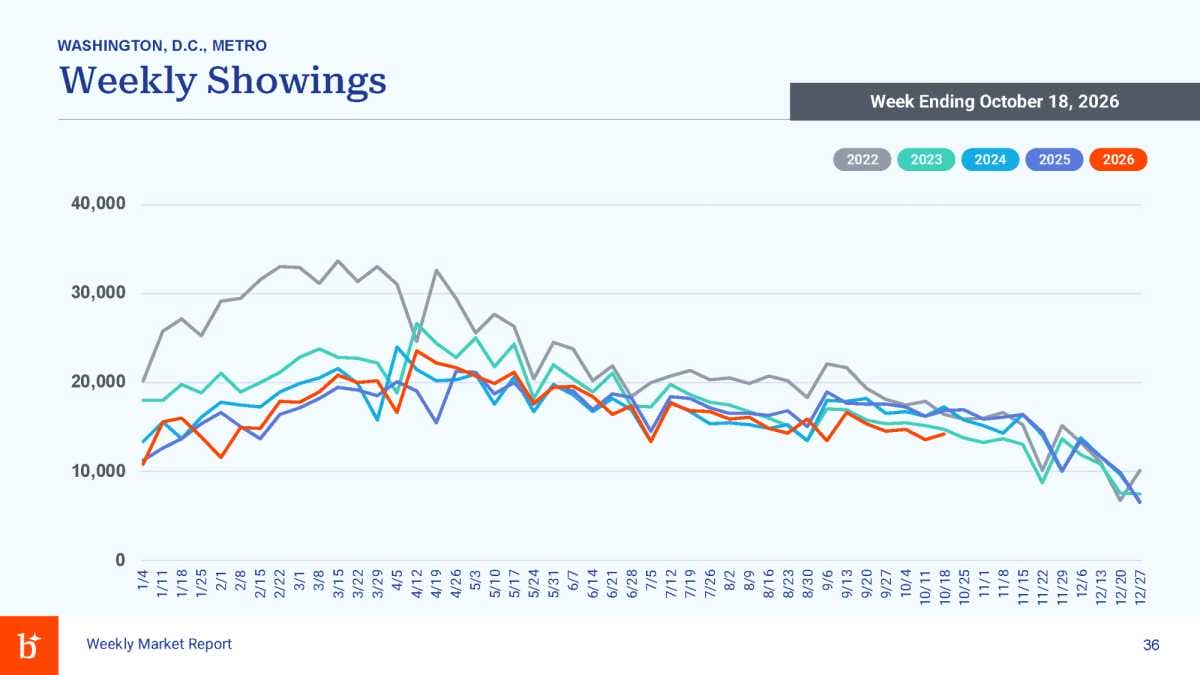
Showing Volume Down Significantly in the DC Metro

Weekly showing volume in the DC Metro has been running at its lowest rate in 5+ years since the beginning of September. Last week, showings were down 16% year-over-year (YoY).

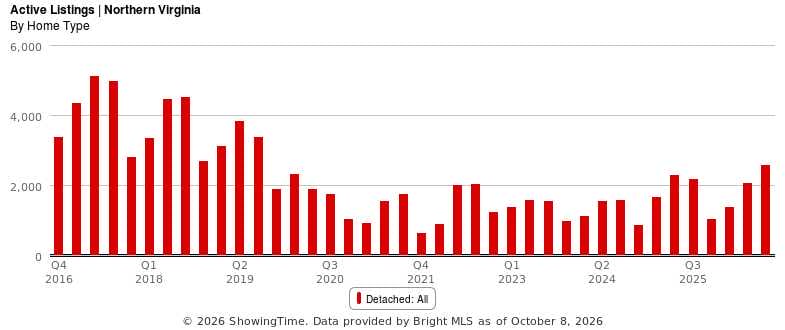
Most Detached Homes Available in Seven Years in Northern VA

There haven’t been this many single-family detached homes available for sale in Northern VA since October 2019. The number of detached homes for sale in Q3 increased by 38% YoY in 2025 and another 17% in 2026.

That said, detached inventory levels are still well below pre-pandemic levels.

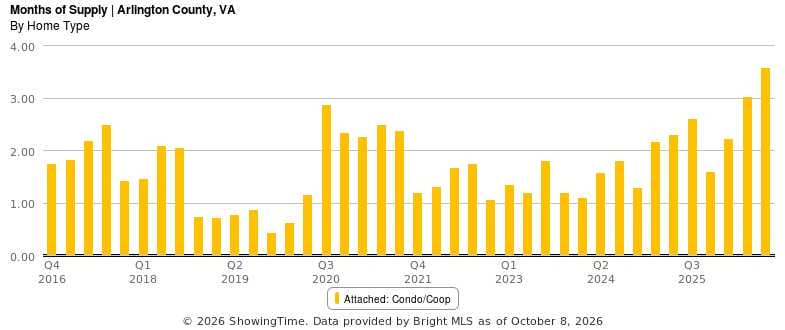
Months of Supply at Ten-Year High for Arlington Condos

The Arlington condo market has the highest Months of Supply (a measure of supply and demand) readings and lowest absorption readings in over ten years. Expect these trends to continue at least through the end of the year, with MoS going higher and Absorption dropping further.

If you’d like to discuss buying, selling, investing, or renting, don’t hesitate to reach out to me at [email protected].

We have access to the most pre and off-market listings across the DMV of any brokerage and are happy to share what’s available with anyone who asks.

Below are some of our team’s pre/off-market listings, details and additional listings available by request:

  • Arlington VA (Barcroft) – 4BR/2BA/2,500 sqft – Detached Single Family – 4th St S Arlington VA 22204

  • Arlington VA (Chain Bridge Forest) – 6BR/6.5BA/7,000 sqft – Detached Single Family (2027) – River St Arlington VA 22207

  • Fairfax VA – 6BR/6.2BA/7,000 sqft – Detached Single Family (2027) – Taylor Dr Fairfax VA 22032

  • Mclean VA – 5BR/4.5BA/3,700 sqft – Detached Single Family (2023) – Randolph Rd Mclean VA 22101

  • Annandale VA – 4BR/3.5BA/2,000 sqft – Townhouse – Aspen Hill Ct Annandale VA 22003

Eli and his team believe that your real estate needs should be managed by advisors, not salespeople. Their mission is to guide, educate, and advocate for their clients through real advice, hands-on support, and personalized service.


This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

Question: We just finished our home inspection and are overwhelmed by the list of recommended repairs. How do we know what to ask for and what’s reasonable to expect from the seller?

Answer: You should expect an inspection to turn up a list of issues, even for a new home. With the market shifting towards more leverage for buyers, inspection contingencies and negotiations are becoming more common. The challenge is figuring out which findings deserve further investigation or negotiation and which belong on your maintenance list after moving in.

An inspection report gives you information to make that decision, but it doesn’t automatically make every item the seller’s responsibility. In my opinion, the goal is to focus on issues that were uncovered that you didn’t account for when you negotiated the purchase contract.

Start With Your Contract

An inspection contingency can be structured in multiple ways. You may have a negotiation period that allows you to ask the seller for repairs or credit or you may just have the right to void, without a built-in negotiation period. The former is favored by buyers, the latter is more attractive for sellers. Having permission to conduct an inspection does not, by itself, establish a right to cancel the purchase.

Your options depend on the agreement you signed. Make sure you understand them before assuming you can keep negotiating or walk away.

Focus on the Findings That Matter

An inspection report can make a minor electrical issue and a foundation concern look equally alarming but they deserve different responses.

The issues I would focus on include:

  • Structural problems

  • Water penetration

  • Safety hazards

  • Systems or appliances that aren’t working properly

  • Conditions that suggest a substantial repair or replacement is coming sooner than expected

Account for Age and Condition

You should try to establish the age and condition of major systems before making an offer, then use the inspection to verify what you understood.

You’ll have a tough time convincing most sellers to buy you a new water heater simply because the existing one is 17 years old, assuming it works and its age was disclosed before your offer. That future replacement should already be part of your ownership budget.

The discussion changes if the inspection finds that it’s leaking or otherwise failing. Similarly, a roof that was represented as recently replaced but turns out to be near the end of its useful life creates a different negotiation than an older roof everybody knew about.

Decide Between Repairs and a Credit

Often, an inspection agreement includes some repairs by the seller and a credit toward the buyer’s closing costs for other items.

For a straightforward repair, having the seller complete the work before closing may be convenient. Be specific about the work, the appropriate contractor qualifications, documentation, and how completion will be verified.

(more…)


This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

Question: How would you compare current weakening market conditions to what happened in 2022, when rates increased quickly?

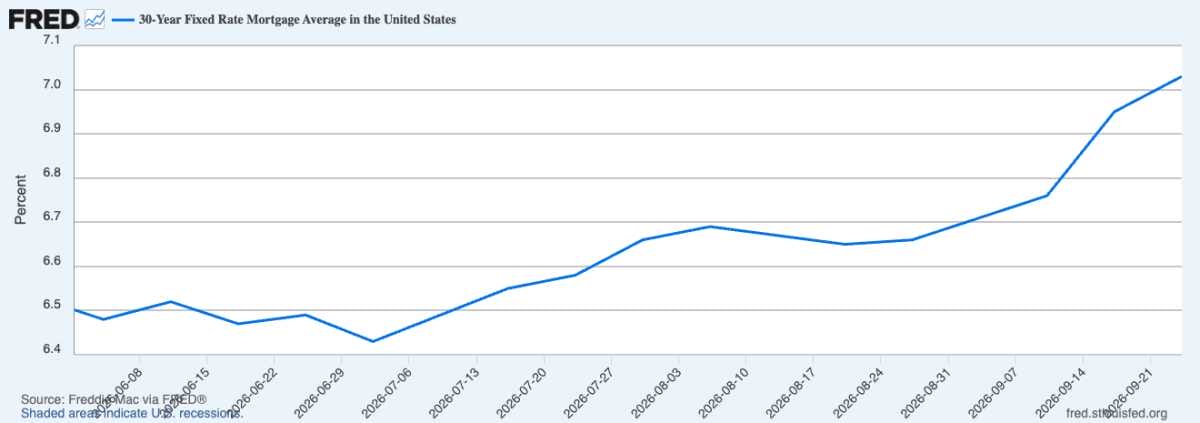
Answer: The DC Metro/Arlington real estate market has slowed considerably, driven by mortgage rates that have climbed since July, rapidly in September. Showings are down, listings are taking longer to sell, and buyers have become increasingly cautious.

Average 30yr Fixed Rate Mortgage in the US since June 1 2026

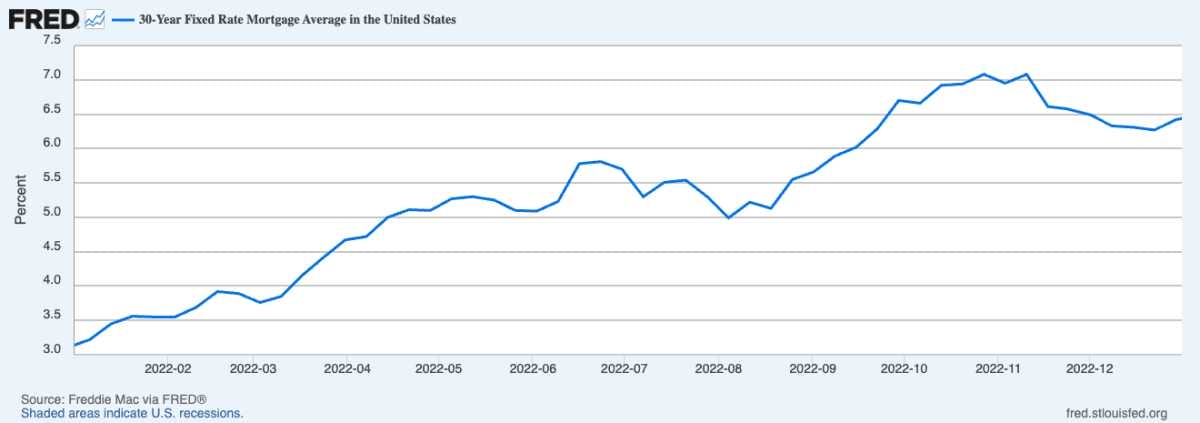
The obvious comparison is 2022, when mortgage rates rose at extraordinary speed and abruptly ended one of the most competitive markets we have ever experienced. The current rate increase is much smaller, but it’s having a significant effect because the 2026 market was in a more vulnerable position than in 2022.

Average 30yr Fixed Rate Mortgage in the US in 2022

The 2022 rate shock hit a market with extraordinary buyer demand and almost no available inventory. Buyers were eager to purchase a home.

The 2026 market has less cushion than in 2022. Rates and prices made payments more uncomfortable, buyer enthusiasm was lower, and we had considerably more inventory relative to demand.

What happened in 2022

During the first half of 2022:

  • 60% of Arlington homes went under contract within ten days

  • Median cumulative days on market was seven

  • Nearly 69% of homes sold at or above the original asking price

  • Almost 49% of homes sold above the original price

  • Only 14% of homes required a price reduction

By the second half of 2022:

  • The share going under contract within ten days fell to 34%

  • Median cumulative days on market increased to 21.5 days

  • Only 34% sold at or above the original price

  • Price reductions increased to 36%

  • The share selling below 95% of the original price tripled from 9% to 27%

Some of that reflects normal seasonality, but the same-period comparison confirms a substantial shift. Compared with the second half of 2021, sales fell 33%, the share selling at or above the original price declined eleven points, and price reductions increased six points.

However, prices did not collapse. The median sale-to-original-ask-price declined from 99% to 97.7%; a modest price correction. The larger correction occurred in transaction volume, competition, and buyer leverage.

Less demand cushion to absorb a smaller rate shock

The first half of 2026 was strong by most historical standards, but it was less competitive than early 2022. Sales volume was 22% lower, the share selling at or above the original price fell from 69% to 59%, and the share selling above the original price declined from 49% to 37%.

Months of supply (a metric that measures supply and demand) shows the difference clearly. During July and August 2022, Arlington averaged 1.5 months of supply (lower MoS favors sellers). During the same months of 2026, it averaged 2.5 months of supply, approximately 60% higher.

(more…)


This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

Question: Do you have guidance for choosing a Title Company to work with when buying or selling a home?

Answer: Title companies manage the legal side of the transaction like ensuring buyers have clear ownership after closing, reviewing and recording the deed, issuing title insurance, and preparing paperwork for the buyer and seller to sign at closing. They work in the background of transactions and, usually, the less you hear from them, the better. In the DMV, title companies generally do not represent one party; they are a fiduciary to the transaction (support both parties).

Locally, it is common for buyers to select the title company. Sometimes, a seller may want to use their own firm/attorney and will request a “split settlement” but that is uncommon.

Your Real Estate Agent, But Ask Why

Among the reasons you’d hire an agent should be their network of professionals that support a real estate transaction: title, lending, inspections, contractors, etc.

If you have an agent, they should be the first person you turn to for a title company recommendation. They’ve probably worked with dozens of local firms before and should have a vetted service partner.

It’s perfectly fair to ask your agent why they’re recommending a title company to make sure it’s for the right reasons. Some agents and brokerages benefit financially from doing business with title companies and it’s important that you know if a financial relationship exists.

Fees

Title insurance is typically the largest fee, and rates are set by the insurer, not the title company. Rates are usually similar, so large differences may reflect basic vs. enhanced coverage. Buyers can choose the coverage level; or whether to purchase owner’s title insurance at all.

Discretionary fees charged by the title company usually don’t vary by more than a few hundred dollars. You can always find a cheaper option for title services, but the quality of legal/title support on a real estate transaction may not be a smart place to save a few hundred dollars.

Location

Use a local title company who is familiar with the local real estate and tax practices, not just licensed to practice here. I use a different title company in Northern VA than I do in Washington DC or Maryland.

Office locations matter less than you’d think because most title companies will support virtual (like a Zoom meeting) or mobile (send a notary to you), but most consumers like closing in an office so check where they conduct closings to make sure it’s convenient.

Attorney Experience

Most sales follow a standard, predictable process that inexperienced title companies/attorneys can handle but occasionally something unexpected comes up that requires experience and expertise to resolve. If problems do surface, having access to an experienced local title attorney makes a big difference in keeping a deal on track and reducing the risk, stress, and effort of all parties.

(more…)


This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

Question: I am debating whether to sell my home or hold onto it as a rental property, do you have any advice?

Answer: Homes are spending more time on the market right now, especially condos, giving homeowners more time to ponder whether or not they should remain on the path to sell or whether they should flip to a rental. I’ll share some tips and advice for anyone in the fortunate position to decide between selling or renting their primary residence.

Start with the Capital Gains Tax Exemption

Spouses filing jointly are exempt from paying taxes on up to $500,000 in capital gains and individuals are exempt from $250,000 if your home has been your primary residence for at least two of five years prior to the sale. In simple terms, assuming you’ve lived in your home for at least two years, if you decide to rent it out for more than three years, you lose your capital gains tax exemption.

Capital gains are calculated by the amount you sell for less your original purchase price less any transaction costs and capital improvements during your ownership, and any depreciation recapture, if it was ever a rental. It is not based on your mortgage balance.

For those with significant capital gains, this exemption is worth a lot of money so in a rent vs sell decision, make sure that if you rent, you are renting for long enough to generate enough value to offset the lost tax benefit.

I generally do not recommend renting for two years and then selling before the three-year mark because there’s risk, cost, and effort involved in renting that usually is not worth two years of rental value.

Don’t Confuse a Capital Gains Exemption with a 1031 Exchange

People often confuse the capital gains tax exemptions with a 1031 exchange. The capital gains exemption is a full tax exemption, up to $250k/$500k, on the sale of a primary residence. A 1031 exchange is the deferral of taxes on the sale of an investment property, only if the proceeds of that sale are used towards the purchase of another “like-kind” investment property. A 1031 exchange does not apply to a sale or purchase involving a primary residence.

Questions to Ask Yourself

There are a series of questions and thought exercises I recommend when making a rent vs sell decision for your home, including:

  • What will you do with the money? If you are using sale proceeds to buy a long-term primary residence or significantly improve your life (e.g. early retirement), selling tends to make overwhelming sense. If you are simply investing the money, the decision is primarily a comparison of different investment vehicles/assets.

  • What does the rest of your investment portfolio look like? Will it benefit from the diversification of a real estate asset? Real estate assets are unique in that they can create income and value growth (appreciation) at once, sort of like a growth stock with good dividends, which is a unicorn in the investment world.

    (more…)


This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

Question: It seems like listings lingered on the market longer than usual this summer. Is that reflected in the market data?

Answer: The summer real estate market is usually slower than spring, but since late June, this summer has felt unusually slow compared with past summer markets. I analyzed Arlington homes listed for sale in July and August, going back to 2016, and found that we did indeed experience a historically slow summer market.

5-Bullet Cliff Notes

  • Summer 2026 was slowest summer market since 2016
  • Showing activity is down significantly
  • Listing supply (homes for sale) is up significantly
  • It is still a seller’s market, just more balanced
  • Too early to accurately observe impact on prices

Slowest Summer Since 2016

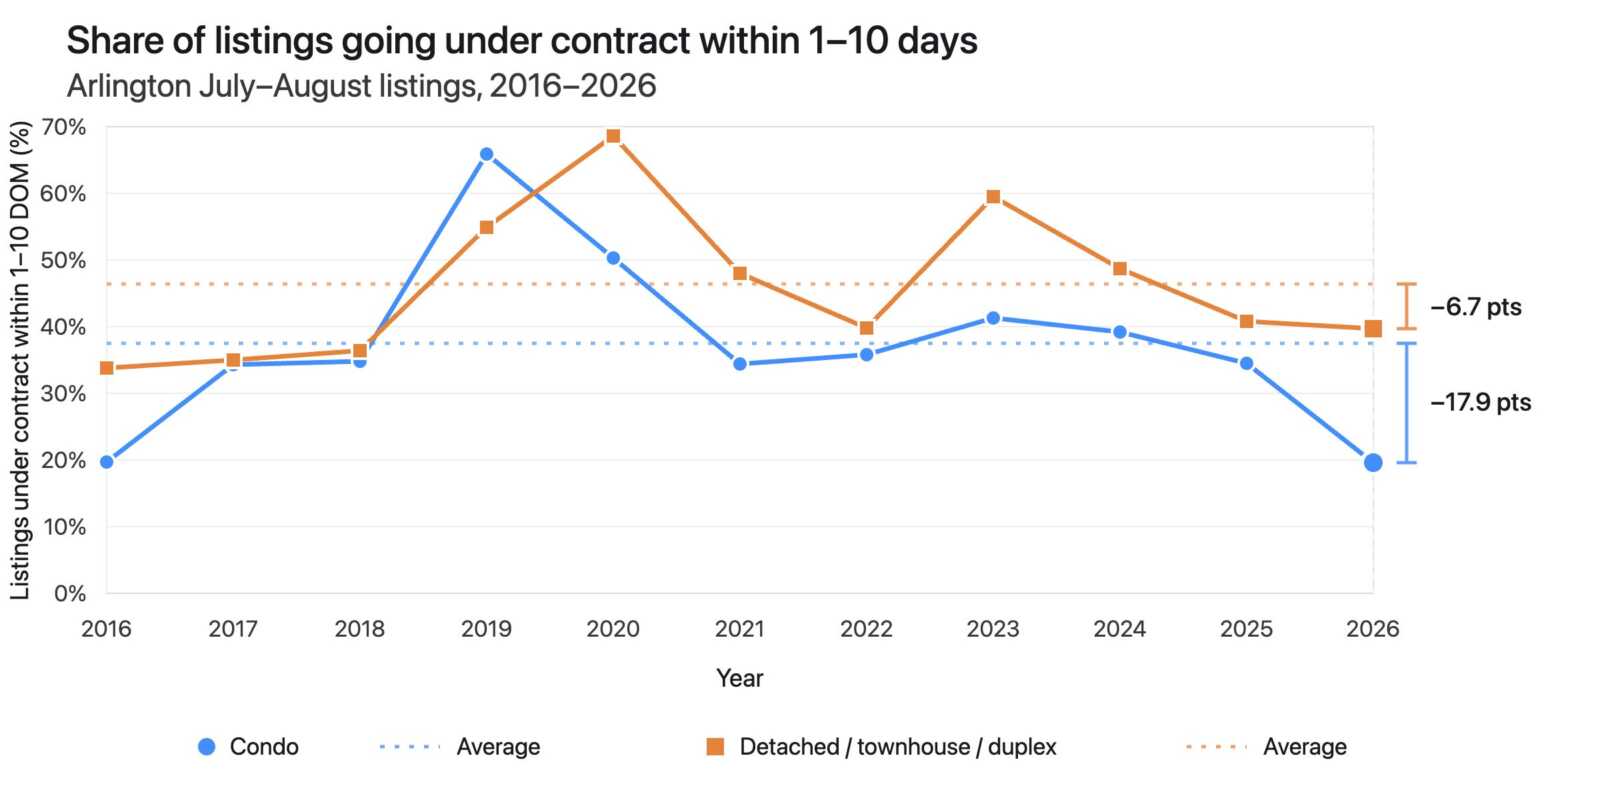
Fewer homes listed in July and August went under contract within the first ten days on market (my preferred measure of market pace) than any summer since 2016.

The condo market experienced the brunt of that slowness, with the percentage of condos under contract within ten days falling 17.9 points below the trailing ten-year average. Arlington’s detached/townhouse/duplex market, one of the most robust sub-markets in the country, was not spared either; falling 6.7 points below the trailing ten-year average.

Lingering Inventory

The clearest sign of a summer slowdown is the amount of inventory that remained unresolved at the end of August. 53% of the listings entered in July and August were still active, compared with about 31% in 2025 and 27% from 2023-2025.

Even among July listings, which had at least a full month to attract a buyer, 36% remained active: more than twice the recent three-year rate. As of Aug 30, ~25% of all active summer listings had accumulated at least 30 days on market, and 9% accumulated at least 60 days.

Showings Down, Active Inventory Up

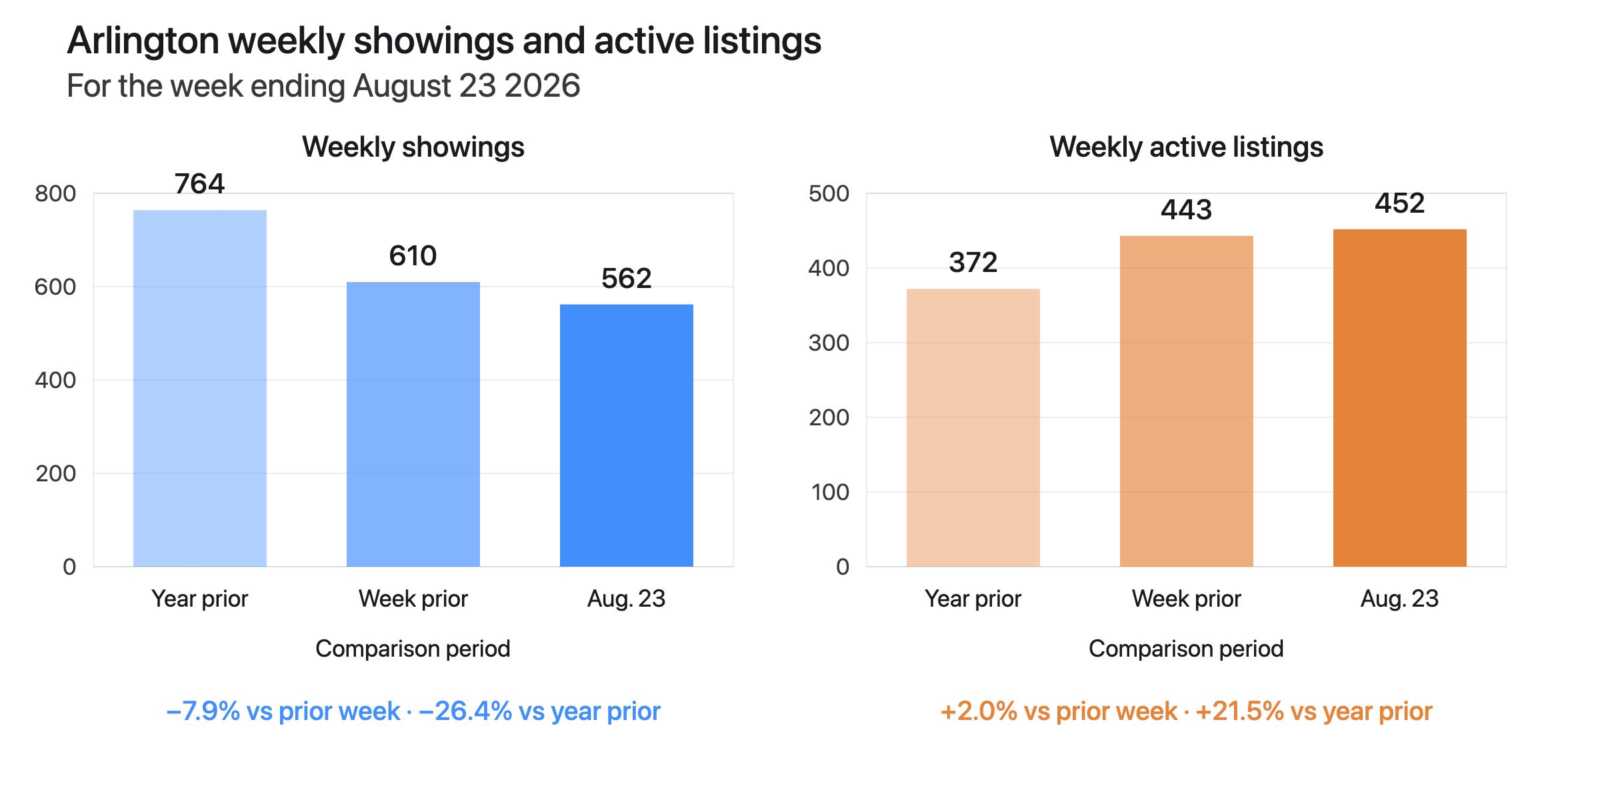
Showing data shows that we have fewer buyers in the market, not simply more indecisive/deliberate buyers. In the week ending August 23, showings in Arlington were down 7.9% from the prior week and 26.4% from the same week last year.

There are also a lot more homes for buyers to choose from, with active listings (homes listed for sale) up 2% from the week prior and 21.5% from the same week last year. Buyers will take longer to make decisions when they have more choices.

The Arlington trends are consistent with other Northern VA/DC Metro markets as well. In the DC Metro, weekly showings dropped to five-year lows in late June and remained there during most weeks of the summer. At the same time, the week ending August 23 delivered the most new listings to the market of any year since 2021, for the same week.

Total active listings in the DC Metro have been above the same week in the prior year since the second week of January 2025.

(more…)


This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

Question: How can my condo Association meaningfully reduce its expenses?

Answer: The Master Insurance policy is often the largest, or one of the largest, annual expenses for a Condominium Association and managing it is critical to keeping stable condo fees. Recently, skyrocketing insurance premiums have put tremendous pressure on Association budgets, but good news has finally arrived for condo owners and Boards.

Today’s column is written by Andrew Schlaffer, Founder and President of ACO Insurance and someone I recommend to any condo Board that wants to inquire about their existing or a new master insurance policy (condo or HOA). You can reach Andrew at [email protected] or (703)595-9760.

Take it away Andrew…

After three to four years of double-digit renewal increases, the condominium insurance market is genuinely improving. Commercial property insurance premiums nationally declined in early 2026, for the first time since 2017, according to a survey by The Council of Insurance Agents & Brokers.

For well-maintained, low-claim condo buildings, we’re seeing typical renewal increases of just 2% to 5% — a dramatic change from the 10%+ increases that were common over the past several years. Water damage remains the leading source of claims for the DMV’s aging condo buildings, followed by fire and wind/hail, but the overall cost trend is heading in the right direction for many communities.

Reinsurance is Driving the Cost Control
Much of this relief traces back to reinsurance — the backup coverage insurance companies themselves buy to protect against catastrophic losses. Reinsurance capital is at record levels, and reinsurance rates fell by double digits over the past year as capacity grew, according to industry reinsurance renewal reports. As reinsurers compete harder for business, carriers are passing some of those savings down to condo associations in the form of smaller increases — and in some cases, outright rate decreases.

Cost Control is not Applied Equally
That said, underwriting scrutiny remains high, and not every building benefits equally. Carriers continue to favor newer, fire-resistive buildings with full NFPA 13 sprinkler systems and newer roofs. Older, garden-style condos with a single means of egress and no sprinklers remain a difficult class to place, since the carrier market for these buildings is thinner, competition is lower, and claims frequency tends to run higher.

If your building falls into this category, it’s generally best to stay with your current carrier unless you receive a double-digit increase — shopping the account in this segment can do more harm than good.

The umbrella/excess liability market hasn’t seen the same relief. Nuclear verdicts (jury awards over $10 million) continue rising sharply, keeping capacity tight and rates firm, according to 2026 liability market data. Expect umbrella/excess liability increases in the 10% to 30% range depending on your community’s loss history and risk profile.

Pillars of Insurance Reviews
Condo insurance reviews require a holistic approach, so it’s important to break the cost into a few distinct categories: insurance premium, deductible expense, and out-of-pocket costs. To effectively accomplish long-term savings, all three of these categories need to be considered and addressed with a qualified insurance professional.

(more…)


This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

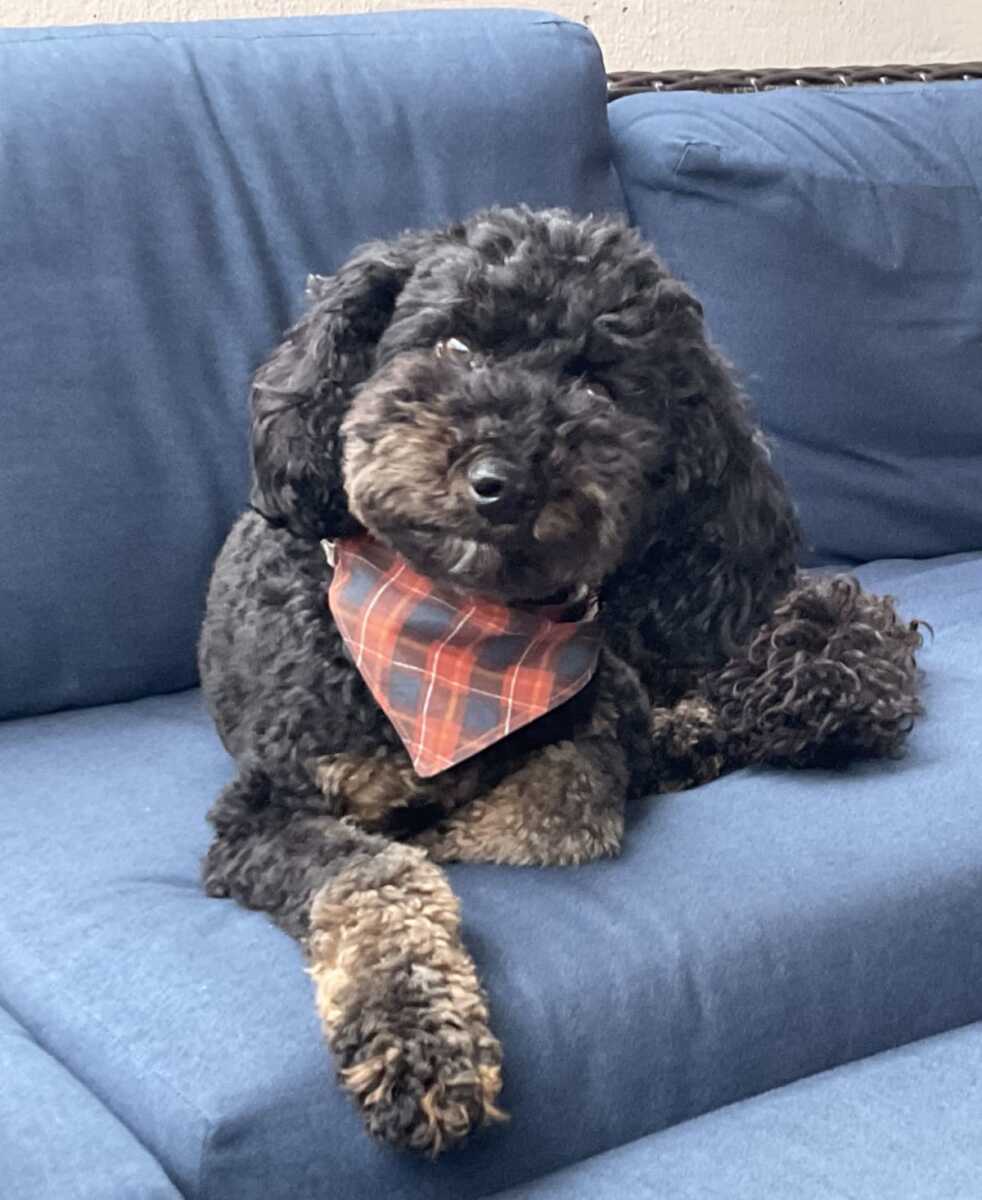
On Friday, I learned that the house fire at the Hyde Park condominium in Ballston was the home of my friend, Greg, his wife Caroline, and their beloved dog, Maisie. I’m sure you saw it in Wednesday’s ARLnow news cycle.

Greg and Caroline were not home when the fire occurred, but they tragically lost their dog Maisie, a loss that overshadows the loss of their personal belongings.

A Bit About Maisie

Maisie lived in the Ballston neighborhood since she was born almost six years ago. She loved meeting old friends and new, between her walks at home and her frequent training walks in Old Town, she had more than either of her parents did. She loved every dog and cat and person she ever met, but she never got over her mistrust of squirrels.  She will be missed as much as she was loved.

Support Lost Dog Rescue in Honor of Maisie

Please consider donating to Arlington’s Lost Dog & Cat Rescue Foundation in Maisie’s memory.

Lost Dog & Cat Rescue Foundation is celebrating its 25th anniversary this year and is an exemplary nonprofit that helps homeless pets find their way to loving homes through rescue and adoption.

There is nothing Greg and Caroline would appreciate more than knowing that Maisie’s memory is helping support the well-being of other dogs and cats.

Leave a Kind Word for Greg and Caroline

If you would like to share well wishes with Greg and Caroline, please leave a comment, and I’ll make sure it gets back to them.


This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

Question: How has the Arlington condo market performed in the first half of 2026?

Answer: After a down year for condo prices in 2025, values rebounded close to 2024 levels despite properties staying on market longer and fewer condos selling for at or above their original asking price.

Market Values Higher, Despite Difficulty Selling

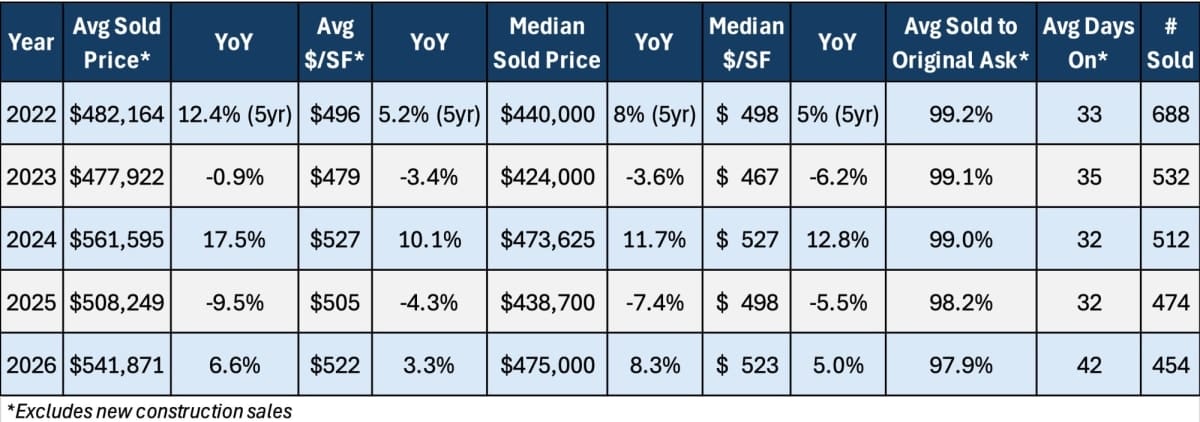
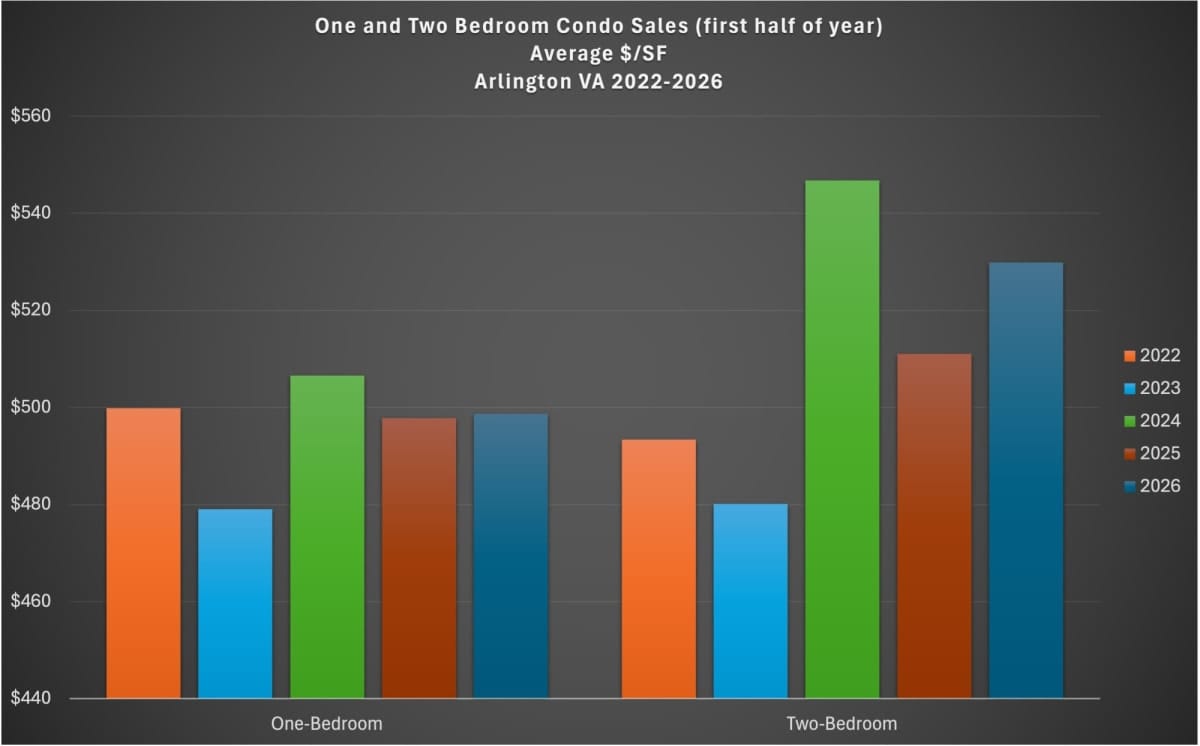
  • The average and median $/SF increased 3.3% and 5%, respectively
  • The average and median price increased 6.6% and 8.3%, respectively
  • Over the past five years, the average and median price per square foot increased by just 5%
  • Sellers felt more pressure during the sale, with the average condo taking an extra ten days to sell (42 days on market) and buyers negotiating an average of 2.1% off the original asking price, compared to 1.8% in 2025
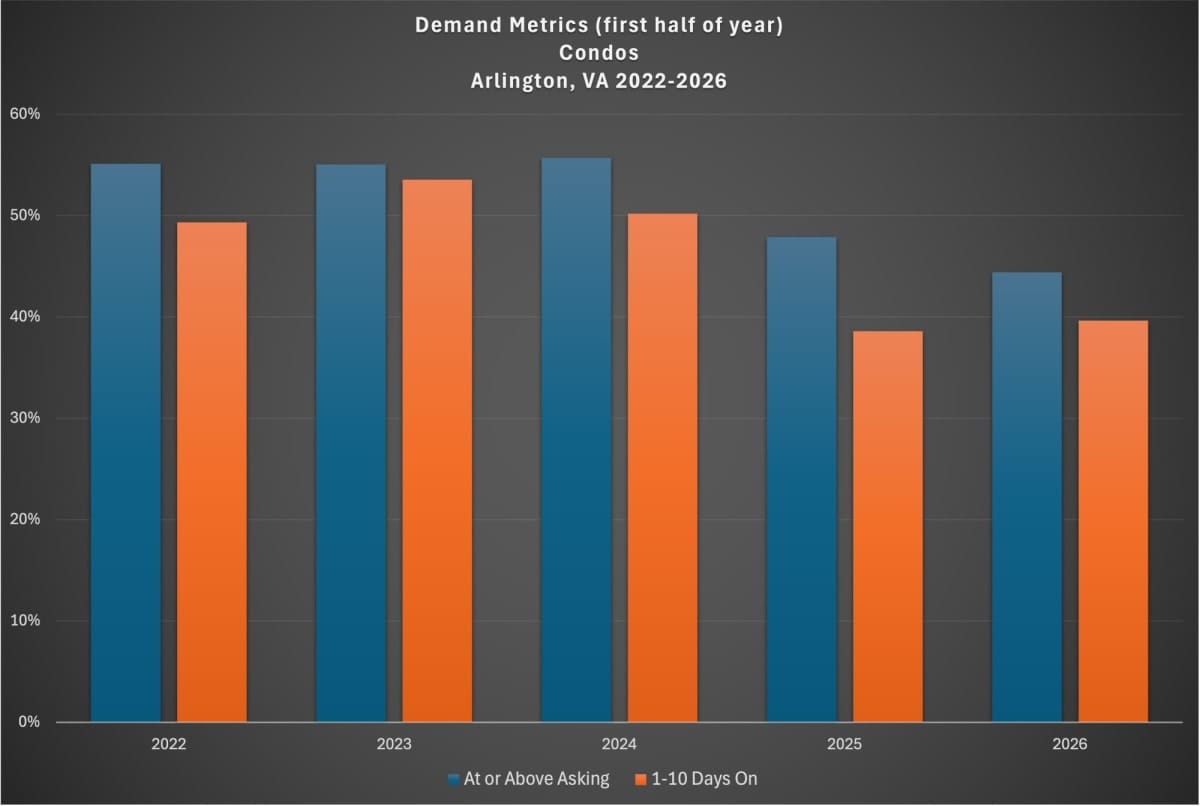
  • Just 40% of condos sold for at or above the asking price, compared to 39% last year and ~ 50% from 2022-2024.

One-Bedroom Values Flat/Stable, Two-Bedroom Values Higher but Volatile

  • In 2026, the average $/SF of two-bedroom condos increased by 3.7%, compared to just 0.2% for one-bedroom condos
  • In 2025, the average $/SF of two-bedroom condos decreased by 6.5%, compared to a decrease of 1.7% for one-bedroom condos
  • The average $/SF of one-bedroom condos are still 1.6% below 2024 values and two-bedroom condos are 3.1% below 2024 values

Condo Fees Play a Significant Role in Condo Sales

The median monthly condo fee increased 3.6% to $638. On a fee-per-square-foot basis, the median rose 0.5% to about $0.70.

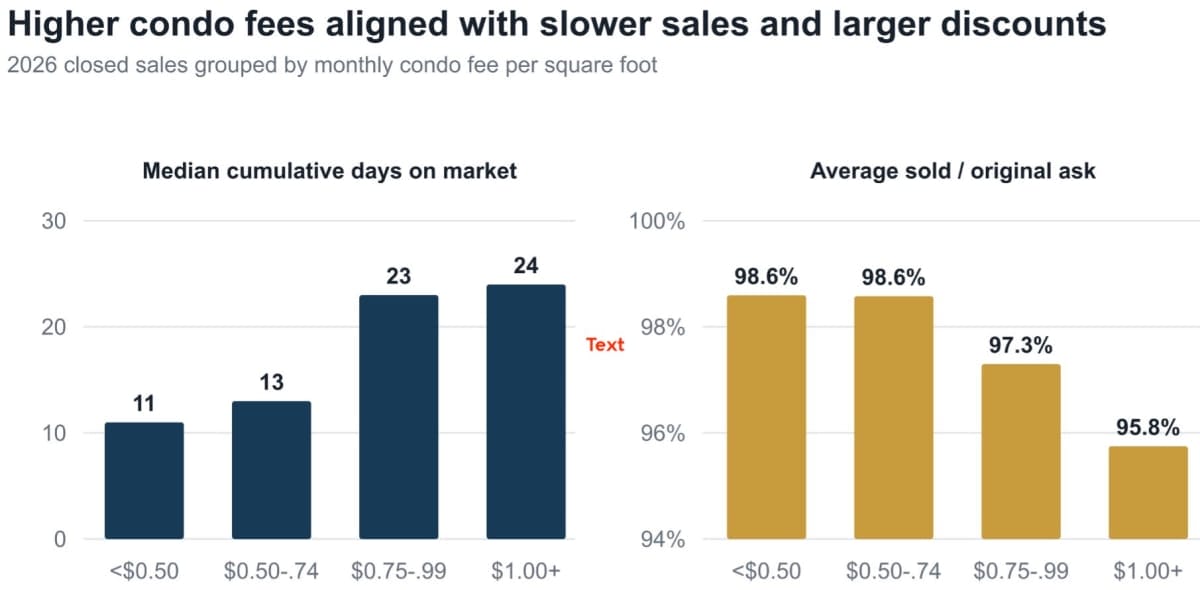
Among 2026 sales with fees below $0.50/SF, the median market time was 11 days, 51.4% sold at or above original ask, and the average sale was 98.6% of original ask. At $1.00+/SF, the median time on market more than doubled, only 35.6% sold at or above ask, and the average sale was 95.8% of original ask. Price reductions were also more common: 32.2% versus 22.9%.

Looking Forward

Given that price growth was attributable to two-bedroom condos, not the entire condo market, and it occurred with key demand metrics well below long-term averages, I wouldn’t be surprised to see values recede in the second half of 2026.

Additionally, condo inventory in Q2 of 2026 was 37% higher than in Q2 2025, while absorption rates were down. More supply combined with less demand is another indicator of downward pressure on condo values in the second half of 2026.

How the Data is Organized

For my mid-year reviews, I like to compare the first half of the year to the first half of prior years, rather than comparing the first half of the current year to the full year in prior years. We tend to see a stronger market (higher demand, more competition) in the first half of the year than the second half, so this approach gives us a better apples-to-apples comparison.

(more…)


This regularly scheduled column is written by Eli Tucker, Arlington-based Realtor and Arlington resident. If you would like to work with Eli and his team in Northern Virginia and the greater D.C. Metro area, you can reach him directly at [email protected].

Question: How has the Arlington single-family home market performed in the first half of 2026?

Answer: Arlington’s single-family detached (SFD) market got busier and more competitive in the first half of 2026, yet prices increased at their slowest pace since 2023.

More Competition, Modest Appreciation (Resale Market)

Note: this data is for resales of single-family detached (SFD) homes; I have a separate analysis of the new construction market further down.

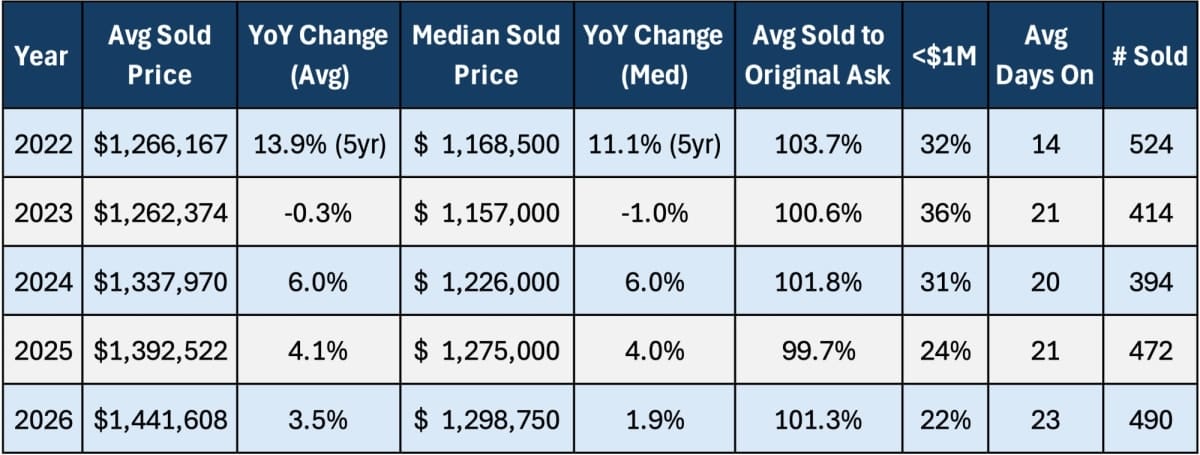
  • The average and median price increased 3.5% and 1.9%, respectively
  • Over the past five years, the average and median price increased 13.9% and 11.1%, respectively
  • The average and median price of a home increased to $1.44M and $1.299M, respectively
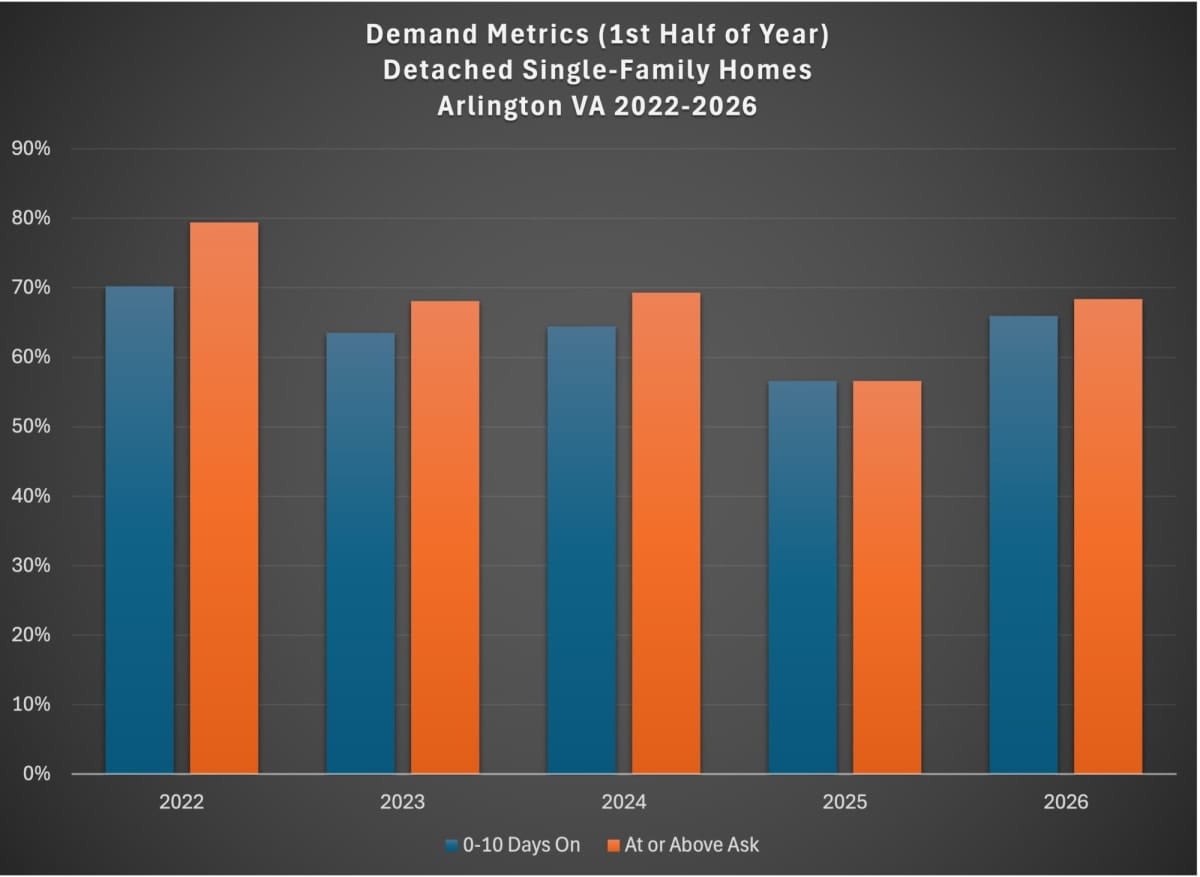
  • Demand and competition rose to the highest levels since 2022, with 66% of homes selling within the first ten days on market and 68% of homes selling at or above the original asking price
  • The average buyer paid 1.3% more than the original asking price, compared to 2025 when the average buyer paid 0.3% less than the original asking price
  • Buyers of homes that went under contract within the first week on market paid an average of 4.7% over the asking price

Dig Deeper: Performance Varied by Size, Price Point

The appreciation gap between the average price (3.5%) and median price (1.9%) matters. The average is more sensitive to expensive sales. In 2026, 15.7% of closed resales sold for $2M or more, up from 12.7% in 2025. At the other end of the market, only 21.7% sold below $1M, down from 24.4%. That shift toward higher-priced homes helped lift the average faster than the median.

Average and median prices are useful, but neither tells us whether gains were shared evenly across the market. To test that, I divided the closed resale market into four sold-price quartiles for each year. Each quartile represents one-fourth of that year’s sales, from the least expensive 25% to the most expensive 25%. (more…)


View More Stories